
Asking your relatives to fund your aviation career isn't an emotional favor; it's a serious business pitch. If you feel a knot in your stomach just thinking about the conversation, you aren't alone. Most aspiring aviators struggle with how to ask family for flight school loan support because they fear being dismissed as dreamers chasing an expensive hobby. That awkwardness is completely normal, but it disappears the moment you replace vague passion with a structured financial plan.
In this guide, you'll learn how to build a professional proposal, address realistic financial concerns, and present flight training as a reliable investment in your future. We'll walk you through a step-by-step presentation framework, legally sound repayment structures, and clear methods to articulate airline pilot earning potential. By the end, you'll have the exact tools and confidence needed to lead an open, transparent financial discussion with the people who believe in you most.
Key Takeaways
- Master the shift from personal favor to career investment by presenting tangible milestones like FAA medical clearance and dedicated personal savings.
- Learn how to ask family for flight school loan support through a structured roadmap detailing your timeline from private pilot ratings to commercial flight decks.
- Protect family wealth and relationships by establishing a formal promissory note aligned with current IRS Applicable Federal Rates to prevent gift tax issues.
- Execute a 5-step presentation framework that gives relatives clear visibility into training syllabi, milestone budgets, and repayment contingencies.
- Validate your proposal through structured academy tracks that provide predictable timelines, institutional accountability, and transparent progress tracking.
Preparing Your Flight School Pitch: Shifting from Favor to Investment
When you begin researching how to ask family for flight school loan support, the biggest challenge isn't the paperwork. It is the mindset. Approaching parents or relatives with an open hand and vague dreams makes the request sound like charity for an expensive hobby. Treat your training as vocational workforce development instead. You are building a tangible career path toward the flight deck, and your pitch must reflect that level of commercial discipline.
Overcoming the Psychological Barrier of Asking Relatives
Talking about money with loved ones creates friction. Family members naturally worry about financial risk, career stability, and high debt loads. Replace their anxiety with clarity. Instead of pleading your passion, address their protective instincts directly by presenting structured airline hiring metrics, commercial retirement forecasts, and transparent industry demand. Demonstrating that you intend to formalize your agreement through a legally binding promissory note signals right away that you value their capital as much as an institutional lender would.
Establishing Upfront Commitment and Personal Investment
Investors want to see skin in the game before committing capital, and your relatives are no different. You build immediate credibility by removing early operational risks before sitting down at the dinner table:
- Secure an FAA First-Class Medical Certificate: Prove your physical qualification upfront. Earning your medical clearance first confirms that underlying health conditions won't ground their investment later.
- Self-Fund Your Initial Ground Milestones: Cover your written exam study materials or early ground school modules out of pocket to demonstrate personal discipline.
- Master the Training Blueprint: Study the exact milestones outlined in how to get your private pilot license in Florida so you can walk your family through each rating stage with absolute clarity.
Mastering these foundational items transforms your request into an actionable proposal. When you understand how to ask family for flight school loan backing as a qualified, motivated candidate with pre-cleared medical eligibility, you turn hesitation into active partnership.
Building Your Aviation Business Plan: Career Timelines and Pilot ROI
Most flight financing discussions fall apart because applicants ask for a lump sum without showing how each dollar translates into career milestones. When planning how to ask family for flight school loan support, your proposal must function like a venture capital prospectus. Show your family the exact link between FAA certificate progression, intermediate earnings, and long-term airline return on investment.
Mapping the Training Progression from Zero to First Officer
A convincing business case breaks down training into clear, distinct funding tranches rather than an open-ended request. Present your flight journey through defined phases, following the benchmarks detailed in the airline pilot career path guide:
- Phase 1: Foundation (PPL): Earn your Private Pilot License to master primary flight maneuvers and basic navigation.
- Phase 2: Professional Ratings (IR & CPL): Complete your Instrument Rating and Commercial Pilot Certificate to legally fly for compensation.
- Phase 3: Instructor Ratings (CFI/CFII): Secure instructor credentials so you can earn a professional wage while building the flight hours required for airline hiring.
- Phase 4: Airline Transition: Step onto a regional flight deck as a First Officer, shifting from learner to commercial airline pilot.
Tying loan disbursements to verified phase completions reassures family lenders that their capital is protected by objective milestones.
Demonstrating Long-Term Commercial Aviation Earning Potential
Highlight the stark contrast between standard four-year college debt and professional aviation careers. While conventional degrees often carry heavy debt with uncertain employment outcomes, commercial aviation leads directly into regulated union pay scales. Entry-level regional first officers earn steady salaries, and senior captains at major carriers earn top-tier professional incomes. This clear wage progression proves your repayment capacity, especially when you structure a defensible schedule tied to current IRS Applicable Federal Rates.
Factoring Regional Training Advantages into Financial Efficiency
Every training delay burns capital through flight currency refreshers and idle hangar time. You protect family investments by choosing high-efficiency environments. Central Florida offers over 300 days of annual flying weather, preventing the seasonal pauses common in northern regions. When comparing facilities against the best flight schools in Florida checklist, highlight how in-house maintenance fleets and high-density dispatch schedules keep training uninterrupted.
When you present how to ask family for flight school loan capital backed by concrete milestones and geographical efficiency, your relatives see a structured roadmap. To explore tailored, career-first training paths that fit this professional framework, consider consulting with aeroglobalaviation.com to solidify your target timeline.
Structuring the Family Loan Agreement: Terms, Promissory Notes, and Taxes
A casual handshake between relatives often leads to friction later. When mastering how to ask family for flight school loan backing, putting concrete terms in writing is the most effective way to protect relationships and preserve household wealth. Approaching your agreement with institutional discipline gives your family confidence that their capital is treated with genuine respect.
Drafting a Legally Binding Promissory Note
A formal promissory note transforms good intentions into an enforceable financial document. Draft a clear agreement detailing the loan principal, designated repayment schedule, interest calculation method, and defined grace periods for late payments. Incorporating specific default conditions and dispute resolution terms clarifies expectations from day one. Sign the document in front of a licensed notary public to validate the agreement for both parties.
Structuring Grace Periods and Milestone-Based Repayment
Flight training requires intensive focus before commercial flight deck earnings begin. Align your cash outflows with realistic career hurdles rather than demanding immediate monthly amortizations:
- Phase-Based Disbursements: Release funds in predefined tranches only after passing specific FAA checkrides during your commercial pilot training syllabus.
- Training Deferments: Establish an interest-only or payment-free deferment period while you complete initial ratings and build intermediate hours as a certified flight instructor.
- Standard Amortization: Begin scheduled principal and interest payments once you secure professional employment at a regional airline or cargo carrier.
Navigating Tax Implications and Protecting the Lender
The IRS monitors private loans closely. If you fail to charge adequate interest, tax authorities may reclassify forgone earnings as a taxable gift. Set your interest rate at or above the published Applicable Federal Rate (AFR). For instance, September 2026 IRS guidelines establish annual rates at 4.18% for short-term notes up to three years, 4.49% for mid-term loans up to nine years, and 5.12% for long-term agreements.
Remind your relatives that interest collected on intra-family loans counts as taxable income, while borrowers cannot deduct interest paid to relatives on their personal tax returns. To offer complete peace of mind, purchase a modest term life and disability insurance policy naming your family lender as the primary beneficiary. Demonstrating this level of foresight proves you know how to ask family for flight school loan resources while thoroughly safeguarding their personal finances.
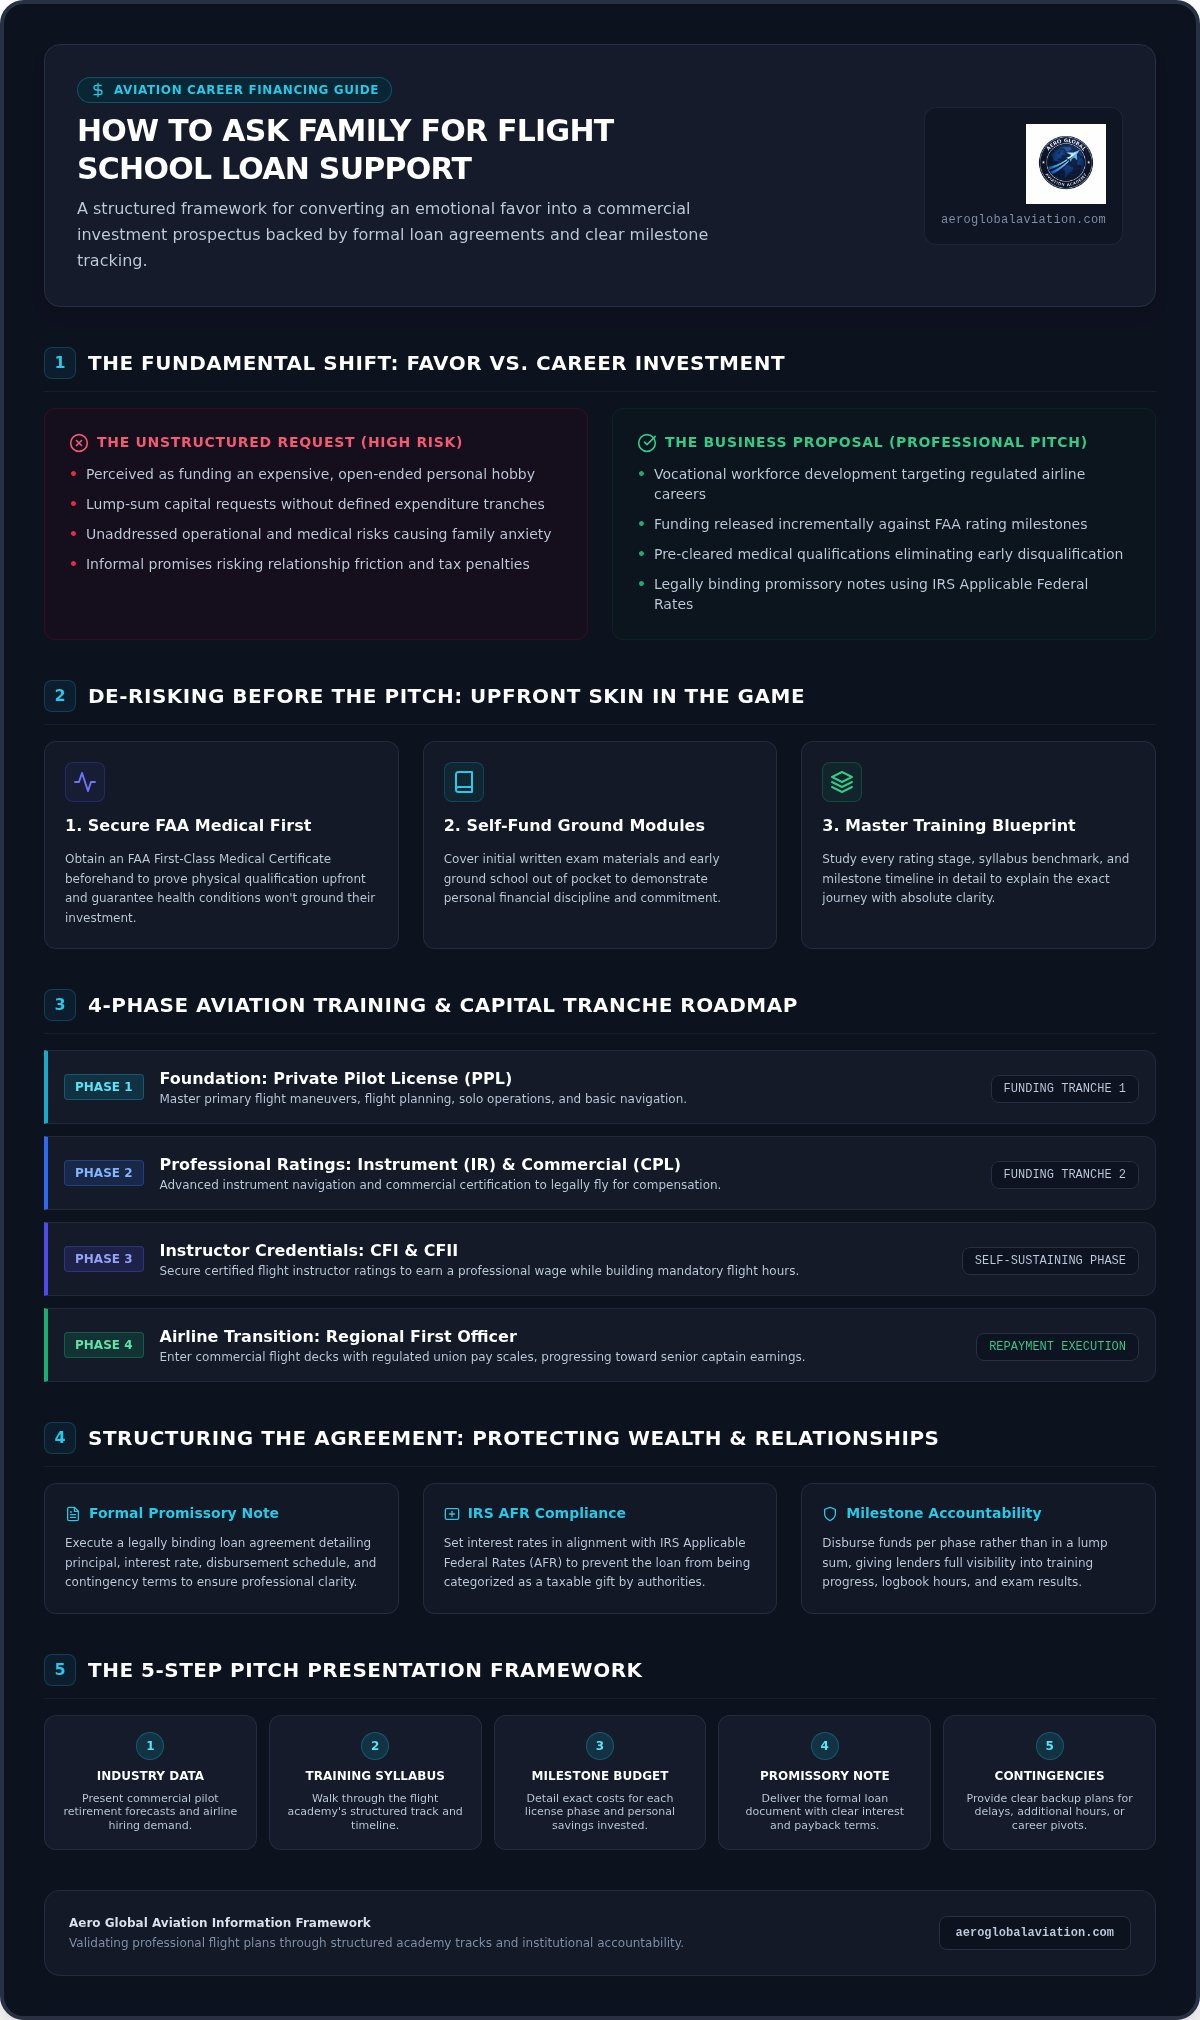
5-Step Pitch Strategy: Present Your Request to Relatives
Timing and presentation matter just as much as your flight aptitude. When you decide how to ask family for flight school loan financing, never bring it up spontaneously during a casual holiday dinner or rushed phone call. Instead, approach the conversation as an executive briefing using this five-step presentation strategy:
- Step 1: Schedule an intentional, distraction-free meeting. Set a specific time and quiet place to review your professional goals together.
- Step 2: Walk through a comprehensive presentation binder. Share printed course outlines, verified timelines, and financial models.
- Step 3: Propose flexible, hybrid funding structures. Blend your personal savings, external scholarships, and family assistance.
- Step 4: Answer tough risk scenarios head-on. Address checkride retakes, industry downturns, and worst-case repayment protections.
- Step 5: Establish clear next steps without demanding an instant answer. Give your relatives at least one to two weeks to review the numbers privately.
Preparing the Professional Aviation Proposal Binder
Handing over a tangible binder transforms abstract ambition into concrete proof. Organize your materials logically. Include your FAA First-Class Medical clearance, personal banking statements showing your initial contributions, and the exact syllabus from your prospective flight academy. Add itemized expense estimates that account for ground school equipment, headsets, FAA written exams, and practical checkride examiner fees so your family sees total fiscal transparency.
Handling Difficult Objections and Managing Risk Concerns
Expect tough questions about the realities of flight training. Address failure rates candidly: explain that students who fly regularly and follow structured curricula progress efficiently without excessive remedial hours. Highlight long-term workforce trends, such as mandatory airline captain retirements at age 65, which keep hiring pipelines active. Most importantly, detail your downside contingency: if an unexpected issue prevents you from completing training, outline exactly how you will return to conventional employment to repay every dollar borrowed.
Structuring Hybrid Financing and Cosigning Alternatives
Do not treat family financing as an all-or-nothing proposition. Ask your relatives to fund the foundational ratings, then plan to secure institutional aviation loans or merit scholarships for multi-engine and advanced stages. If family members are hesitant to lend cash directly, ask if they would consider serving as a creditworthy cosigner on a dedicated aviation education loan instead. Demonstrating that you have applied for independent pilot grants shows genuine resourcefulness.
Learning how to ask family for flight school loan backing requires showing operational maturity before you ever start an engine. To review structured career footprints and gather authoritative program materials for your presentation binder, visit aeroglobalaviation.com and download our comprehensive training blueprints today.
Partnering with Aero Global: Validating Your Plan Through Elite Training
A business proposal is only as credible as the organization executing it. When you refine how to ask family for flight school loan support, pointing to an established flight academy provides your relatives with institutional oversight and clear accountability. Relatives don't want their savings vanishing into unstructured, pay-as-you-go flying clubs. They want to see professional syllabi, dependable aircraft availability, and experienced leadership overseeing your training timeline.
Aligning Family Capital with Structured Career Programs
Presenting a clearly mapped syllabus proves to your family that their funds are deployed efficiently. Choosing a program like the Career Pilot Program in Kissimmee, Orlando takes you systematically from your Private Pilot License through your Commercial Pilot License. This direct path prevents the fragmented, piecemeal scheduling that inflates training costs. For students targeting immediate instructional employment, the Airline Pilot Elite track carries you all the way through advanced flight instructor credentials, guaranteeing that every dollar borrowed leads directly to a marketable aviation role.
Inviting Family to Experience the Flight Academy Environment
Bring your relatives into the flight environment so they can witness the operation firsthand. Visiting the training base at Kissimmee Gateway Airport near Orlando transforms abstract charts into tangible reality. When family members meet your chief flight instructors, walk the hangar floor, and see active dispatch operations, their protective skepticism often turns into genuine enthusiasm.
- Direct Leadership Access: Introduce your benefactors directly to academy leadership so they can ask tough questions about safety records and completion rates.
- Real-Time Milestone Tracking: Show relatives how your digital logbooks and syllabus stages are monitored, allowing them to track your flight progress as you clear checkrides.
- Shared Discovery Experience: Bring a family member along for an introductory flight so they can experience the aircraft and see your dedication in the cockpit.
Validating your proposal through an elite flight academy is the final piece in learning how to ask family for flight school loan backing with complete authority. Give your family the confidence they deserve: take the next step and schedule a discovery flight or campus tour today to turn your aviation goals into an actionable reality.
Lead Your Aviation Pitch with Confidence
Mastering how to ask family for flight school loan backing doesn't have to be intimidating when you treat flight training as a serious career investment. By establishing a formal promissory note, demonstrating personal skin in the game, and tying funds directly to objective rating milestones, you give your relatives the financial clarity and peace of mind they need to back your commercial goals.
The most effective way to validate your proposal is by anchoring it to a disciplined flight environment. Operating from our Kissimmee Gateway Airport base under year-round Central Florida skies, Aero Global delivers rigorous, predictable training through our Career Pilot Program and Airline Pilot Elite tracks. With personalized mentorship and transparent milestone tracking, your family can watch your transformation from student to commercial flight officer with total confidence. Schedule a campus tour and discovery flight with Aero Global Aviation today, and take the first decisive step toward earning your wings.
Frequently Asked Questions
Is it better to ask family for a direct loan or to cosign a private student loan?
A direct loan is generally cleaner because it avoids high private bank interest rates and origination fees. However, if your family lacks liquid capital to fund training directly, asking them to cosign a specialized aviation loan can serve as an effective compromise. Cosigning still impacts their personal credit score if payments are missed. When learning how to ask family for flight school loan support, present direct lending first, with cosigning as a structured alternative.
What interest rate should I offer to pay my family on a flight school loan?
You should offer an interest rate equal to or slightly above the current IRS Applicable Federal Rate (AFR) for the loan's term length. As of September 2026, the annual AFR benchmarks are 4.18% for short-term notes, 4.49% for mid-term loans, and 5.12% for long-term agreements. Offering this official rate protects your relatives from gift tax penalties while providing them with a fair return higher than standard savings accounts.
How do I reassure my family about aviation industry hiring cycles and job security?
Reassure your relatives by showing long-term attrition figures rather than emotional hype. Focus on mandatory FAA airline pilot retirements at age 65, which create steady demand for newly certified first officers across regional and major carriers. Additionally, demonstrate your plan to build flight hours as a certified flight instructor. This stepping stone generates steady income and professional experience regardless of short-term airline hiring pauses.
What happens to the family loan if I lose my FAA medical certificate?
You should purchase private loss-of-license or disability insurance and list your family lender as the primary policy beneficiary. If an unexpected medical disqualification occurs, the insurance payout covers the outstanding loan balance. Your agreement should also include a written fallback contingency stating that you will secure non-flying employment to fulfill the original promissory note schedule if your aviation career is cut short.
Should we hire a lawyer to write our intra-family flight school loan agreement?
While you can draft a standard promissory note using state-specific legal templates, having a contract attorney review the final draft is wise. A brief consultation ensures your agreement complies with local state lending caps and federal tax rules. Signing the document before a licensed notary public adds an extra layer of legal enforceability. This extra step proves to your relatives that you treat their financial commitment with absolute seriousness.
How can I prove to my family that I have the discipline to finish flight training?
Show clear evidence of discipline before requesting funds. Pass your FAA First-Class Medical exam, study independently for your FAA written ground exam, and maintain steady full-time employment or strong academic grades. If you train locally in Kissimmee, Orlando at Aero Global Aviation Academy, show relatives the structured daily syllabus of the Wings Foundation or Career Pilot Program so they see you are following a rigorous, proven pathway.
Can my family make tuition payments directly to the flight school instead of giving me cash?
Yes, paying the flight academy directly is actually the preferred method for most family lenders. When organizing how to ask family for flight school loan backing, set up milestone-based disbursements paid straight to the flight training provider. For example, your relatives can disburse funds directly to the academy ledger upon enrollment and after each passed checkride. This approach eliminates handling concerns and ensures every dollar funds authorized flight time.


